HomeAuto Samsung Used HBM4 Memory Supply Monopoly to Force AMD Into Foundry Talks
Samsung Used HBM4 Memory Supply Monopoly to Force AMD Into Foundry Talks
October 10, 2026:
Oliver Contreras/gettyimages.com
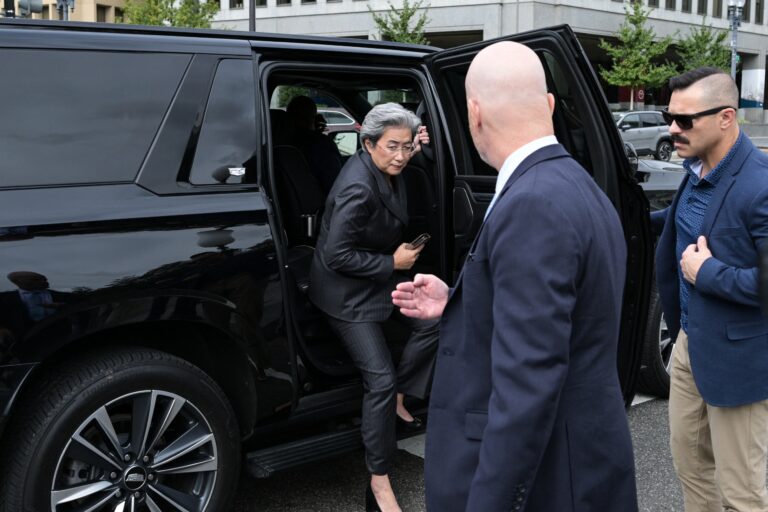
When Lisa Su landed in Seoul on October 7 for the second time in seven months, the publicly stated purpose was memory — locking in multi-year high-bandwidth memory supply for AMD’s Helios AI rack platform, which requires 31 terabytes of HBM4 per system and cannot ship without it. The meetings that day with Samsung Device Solutions head Jun Young-hyun and SK Hynix CEO Kwak Noh-jung were also about something else: whether AMD’s acute need for that memory had finally given Samsung Foundry the opening it needed to break into logic chip manufacturing that AMD had historically taken elsewhere.
According to reporting by TrendForce and the Korean business outlet Chosun Biz, Samsung has explicitly used its position as AMD’s primary HBM4 supplier as a negotiating instrument to advance discussions over manufacturing AMD’s logic chips — CPU and GPU dies — on its advanced SF2P 2nm process. The TrendForce HBM4 foundry leverage report states the specific terms have not been disclosed, and no foundry contract has been announced. But the structure of the negotiation, as described by Korean industry sources, is clear: AMD needed memory it could not source adequately elsewhere, and Samsung used that need as a conversation-opener for a business it had never previously won from AMD.
This is the development that the seven-month timeline of AMD-Samsung talks has been building toward.
Memory as a Negotiating Instrument
The structural logic of Samsung’s position is straightforward. High-bandwidth memory is manufactured at meaningful scale by only three companies — Samsung, SK Hynix, and Micron — and Samsung and SK Hynix together account for the overwhelming majority of global HBM output. SK Hynix, which held approximately 57 to 58 percent of Counterpoint Research HBM market share in the months leading up to AMD’s supply crunch, had already committed the large majority of its 2026 HBM4 capacity to Nvidia. That concentration left AMD structurally dependent on Samsung as its primary HBM4 anchor, and Samsung recognized that dependency as foundry leverage.
Samsung has been trying to win AMD’s logic chip manufacturing business for years. The two companies have a manufacturing relationship dating to 2016, when Samsung produced AMD chips on its 14nm process, but subsequent AMD logic chips went exclusively to TSMC and GlobalFoundries. AMD is among the few remaining high-volume logic customers that Samsung Foundry has not yet claimed at advanced nodes — a gap that Samsung’s foundry business urgently wants to close.
What changed in 2026 is that the HBM crunch gave Samsung a new kind of leverage. “Samsung may use HBM shipments as leverage to secure a partial shift of AMD’s advanced AI chip production to Samsung Foundry,” TrendForce AMD foundry leverage reported in March 2026, citing Chosun Biz. AMD, as TrendForce noted, “has historically been one of TSMC’s most loyal clients” with all advanced-node chips at 7nm and below produced by TSMC — making any shift to Samsung a significant departure from a decade of manufacturing strategy.
What Samsung Is Selling, and What AMD Is Buying
Samsung’s pitch to AMD rests on two assets working together. The first is HBM4 itself: Samsung became the first company to begin Samsung HBM4 commercial production in February 2026, and the March MOU formally designated Samsung as AMD’s primary HBM4 supplier for the Instinct MI455X — the GPU at the heart of the Helios rack. Samsung’s HBM4 is built on a 4nm logic base die and a sixth-generation 10-nanometer-class DRAM process, delivering speeds up to 13 gigabits per second. The MI455X carries 12 such stacks, producing AMD MI455X HBM4 bandwidth of 23.3 terabytes per second of total bandwidth per GPU.
The second asset is Samsung’s SF2P foundry process — its second-generation 2nm gate-all-around (GAA) chip manufacturing technology — which Samsung is currently ramping for mass production in 2026. SF2P is designed to deliver 12 percent better performance, 25 percent lower power consumption, and 8 percent smaller die area compared to the previous SF2 generation. If Samsung can achieve and demonstrate the approximately 70 percent yield rate that chip designers generally require for high-volume production, it would represent a meaningful improvement over the difficulties that plagued its earlier 3nm GAA process and cost it customers.
The integrated pitch is what makes Samsung’s position genuinely unusual. A pure-play foundry like TSMC has process quality to sell and nothing else. Samsung can offer AMD HBM4 supply that no one else is in a position to match at scale, foundry capacity at a moment when TSMC’s advanced-node production is reportedly booked through 2028, and the integrated logic-base-die architecture for next-generation HBM that keeps its memory roadmap and logic roadmap interlinked.
Why Samsung Sees Opportunity in AMD’s Urgency
The timing of Samsung’s leverage play is not coincidental. AMD publicly committed to a significant expansion of its AI accelerator supply in 2026, driven by the July AMD Helios launch announcement of the Helios rack-scale platform — AMD’s first complete answer to Nvidia’s NVL72, combining 72 MI455X GPUs, 18 sixth-generation EPYC Venice processors, AMD Pensando networking, and a 31 TB shared HBM4 memory pool. The Helios ambition requires memory bandwidth that only Korea can supply at the scale AMD needs.
AMD’s second-quarter 2026 earnings underlined the stakes: the company posted AMD Q2 2026 earnings data center revenue of $6.7 billion, up 107 percent year over year, representing more than half of AMD’s record $11.5 billion total revenue. AMD’s CFO stated that data center sales were expected to accelerate through the second half of 2026, with Helios ramp cited as a key driver — a statement that made the question of whether Helios could actually ship at scale one of the most consequential near-term variables in the company’s financial narrative.
Su acknowledged the pressure at AMD’s September appearance at Citi’s Global TMT Conference. “We need to expand supply, but the supply of components such as HBM and semiconductor substrates is very tight, and there are also constraints on advanced packaging capacity,” an AMD executive stated, per Korea Herald reporting. That last clause — advanced packaging capacity — refers to TSMC’s CoWoS-L (Chip-on-Wafer-on-Substrate) process, which bonds the HBM stacks and GPU compute dies onto a silicon interposer and represents a second chokepoint independent of Samsung’s and SK Hynix’s ability to produce the memory stacks themselves.
SK Hynix CEO Kwak Noh-jung, speaking to Reuters SK Hynix warning in July 2026 at the time of his company’s Nasdaq listing, confirmed the broader picture: 2027 will be “the worst year in the industry’s history from the supply perspective,” with customer demand expected to outpace production capacity beyond 2030. For AMD, that timeline means that securing multi-year HBM4 supply now — and not losing Samsung’s cooperation through a failed foundry negotiation — is not a procurement detail. It is a product roadmap constraint.
What AMD Is Prepared to Offer, and What It Is Not
Samsung’s hope of converting memory supply into a foundry relationship faces a credibility challenge that Su has not concealed. AMD’s senior vice president, in an interview with Chosun Biz, described TSMC as “the undisputed leader in 2nm process technology,” a characterization that is accurate by any public performance benchmark. AMD EPYC Venice 2nm — the sixth-generation server CPU, built on TSMC’s N2 process — represents the first HPC chip design to be manufactured at the 2nm node, making AMD one of TSMC’s lead N2 customers.
Against that backdrop, Korean media cited a senior semiconductor industry official characterizing AMD’s view of entrusting foundry work to Samsung as “too risky” — a framing consistent with AMD’s public posture of exploring foundry cooperation without committing to it. Su, speaking to reporters at the October 7 Seoul briefing, said AMD “continues to explore partnership opportunities” in foundry, a formulation that signals interest without disclosure of terms.
The most specific public signal of what Samsung is actually hoping to manufacture came from Daishin Securities, whose analysis — cited by the industry tipster Jukan — suggested Samsung had “apparently won” a 2nm notebook CPU order from a North American fabless customer, with AMD identified as the likely source. If that report is accurate, it implies AMD may have already authorized Samsung to prototype consumer-facing Ryzen processors (reportedly codenamed “Olympic Ridge”) on SF2P, with Helios and EPYC-class AI accelerators potentially following if yield results justify it. The lower product risk of consumer CPUs compared to AI accelerators would make them a logical first step in a dual-sourcing strategy.
AMD’s Washington Role and the Seoul Paradox
Su’s supply chain diplomacy in Seoul is not isolated from her technology policy role in Washington — the two reflect the same structural gap from opposite ends.
In May 2025, Su testified before the Senate Commerce Committee AI hearing at a hearing titled “Winning the AI Race: Strengthening U.S. Capabilities in Computing and Innovation,” calling for “a robust domestic supply chain for advanced semiconductor manufacturing and packaging.” She serves on the Presidential Council of Advisors on Science and Technology under both the Biden and Trump administrations — reappointed by President Trump in March 2026 alongside Nvidia CEO Jensen Huang and Meta’s Mark Zuckerberg — and she chairs the Semiconductor Industry Association board. AMD federal lobbying and PCAST data shows AMD has spent $8.72 million lobbying the federal government on semiconductor manufacturing and artificial intelligence policy since the start of 2025.
The paradox embedded in Wednesday’s meetings is exactly the vulnerability Su identified to Congress: a company powerful enough to testify before the Senate on semiconductor supply chain resilience, and influential enough to advise successive presidents on technology policy, is still dependent on face-to-face meetings in Seoul to determine when its flagship AI product ships at scale. No domestic HBM manufacturer exists at anywhere near the scale needed for AMD’s requirements. No American foundry can match TSMC’s 2nm yield at the volume AMD needs. Policy advocacy has not yet produced the industrial capacity it argues for — and AMD is, in the interim, managing that gap one bilateral conversation at a time.
On October 8, Su extended her Korea visit to a roundtable with the CEOs of Korean AI chip companies Rebellions, FuriosaAI, and Mobilint, and held a separate meeting with Science Minister Bae Kyung-hoon at the Korea Times Seoul roundtable. The breadth of that engagement — from HBM4 supply deals with Samsung to conversations about Korea’s sovereign AI semiconductor ecosystem — illustrates how thoroughly AMD’s most important near-term priorities are rooted in Korean industrial capacity.
The Terms Samsung Needs
Whether Samsung can convert its HBM4 position into a durable foundry relationship with AMD ultimately depends on whether its SF2P process can meet AMD’s performance and reliability thresholds. The first-generation SF2 yield at Samsung, while improving, has reportedly not yet reached the 70 percent threshold that Samsung itself set as its year-end target and that chip designers typically require for high-volume production commitment. TSMC’s N2, by comparison, is reported to be operating in the 60 to 70 percent yield range, closer to the industry standard for reliable high-volume output.
Samsung’s approach to this credibility gap has been sequential: the Tesla Samsung $16.5 billion deal to manufacture AI6 chips at Samsung’s Taylor, Texas facility gives Samsung a high-volume anchor customer for its 2nm process. Success with Tesla’s AI6 would provide the yield and reliability data that AMD needs to evaluate SF2P for its own designs. Samsung’s plan to bring a third-generation SF2P+ variant online at Taylor by end of 2026 for trial production, with full mass production targeted for 2027, would extend the timeline further — but would also provide a US-based manufacturing option that is relevant to AMD’s domestic supply chain policy commitments.
For AMD, the calculus is strategic rather than purely technical. The company’s aggressive data center revenue growth — $6.7 billion in a single quarter — means the cost of a supply-chain failure on Helios is measured in billions of dollars of missed opportunity. Cultivating Samsung as a second credible logic chip manufacturer, even at initially lower volumes than TSMC, represents insurance against TSMC’s already-constrained N2 capacity. And Samsung, for its part, has made clear through the structure of the HBM4 negotiation that it intends to extract foundry consideration in exchange for memory access — a dynamic that AMD’s urgency has made it difficult to resist.
No foundry agreement has been announced. But the structure of the last seven months of AMD-Samsung engagement — the memory MOU in March, the ongoing foundry discussions, the back-to-back CEO meetings in Seoul — describes a negotiation in which Samsung has been deliberate about what it is trading and what it wants in return. AMD’s most important product depends on Korean memory. Samsung has made it clear it would like something else in return.
Frequently Asked Questions
Why is Samsung using its HBM4 supply as leverage to win AMD’s chip manufacturing business?
Samsung’s foundry division has long struggled to attract top-tier fabless chip designers for advanced-node logic manufacturing, losing out to TSMC on most major customers — including AMD, Qualcomm, and Nvidia — in recent generations. The global AI boom created a specific vulnerability: AMD urgently needs HBM4 memory, and only Samsung and SK Hynix can supply it at meaningful scale. SK Hynix has committed the large majority of its 2026 HBM4 capacity to Nvidia, leaving AMD structurally dependent on Samsung. Samsung recognized that dependency as an opportunity to advance foundry discussions that AMD might not have entered from a position of equal bargaining power, as TrendForce AMD foundry leverage documented in March 2026.
What makes HBM4 so difficult to manufacture, and why can only three companies do it?
High-bandwidth memory requires DRAM dies to be thinned to approximately 30 micrometers — about one-third the width of a human hair — stacked up to 16 layers high, and interconnected through copper-filled holes called through-silicon vias (TSVs). Each additional layer compounds the yield challenge: a defect in any die in the stack renders the entire stack unusable. HBM4 doubles the memory bus width from 1,024 bits (HBM3E) to 2,048 bits, requiring additional interconnect precision. The specialized equipment, process expertise, and years of yield refinement required to do this at scale have concentrated commercial HBM manufacturing in Samsung, SK Hynix, and Micron, as documented in the JEDEC HBM4 memory standard.
What does the fabless chip model mean for AMD’s vulnerability to this kind of supply leverage?
AMD designs chips but does not manufacture them — a structure called the fabless model, pioneered when AMD spun off its fabs into GlobalFoundries in 2009. Fabless companies are entirely dependent on third-party manufacturers for both memory and logic chip production. When a single category of component — like HBM4 — is manufactured by only three companies globally, and demand outpaces supply, those manufacturers gain the ability to attach conditions to supply agreements. Samsung’s foundry gambit illustrates the structural vulnerability of the fabless model: as covered in Wikipedia High Bandwidth Memory history, AMD invented HBM memory, standardized it, and built its most important product around it — but it cannot manufacture a single stack and is dependent on the very company using that supply as a negotiating tool.
Could Samsung’s SF2P foundry process actually meet AMD’s manufacturing requirements?
Samsung’s first-generation SF2 2nm process has improved its yield rate to approximately 50 percent, according to Korean media reporting, below the 70 percent threshold that chip designers typically require for high-volume production commitment. Samsung raised its internal year-end yield target to 70 percent in 2026, and the SF2P second-generation process is designed to deliver meaningful improvements over SF2 in performance and power efficiency. Whether Samsung can demonstrate 70-percent-plus yields on the specific chip designs AMD would send — which may include consumer Ryzen processors as a first step, followed potentially by data center products — is the central technical question that will determine whether the memory leverage translates into a real foundry relationship.