HomeAuto Pentagon Backs Wolfspeed With $1.5B Loan to Protect Radar Chips Already in F-35s
Pentagon Backs Wolfspeed With $1.5B Loan to Protect Radar Chips Already in F-35s
October 10, 2026:
Aseem Borkar/pexels.com
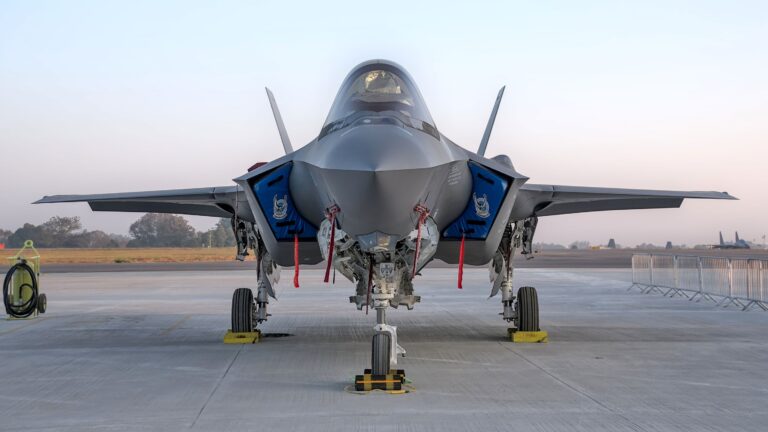
The Pentagon has quietly acknowledged something it rarely says out loud: deployed US weapons systems already depend on a supply chain that nearly collapsed. On October 7, 2026, the US Department of War announced a conditional $1.5 billion, 30-year loan commitment to Wolfspeed Inc. through its Office of Strategic Capital — a defense development finance institution — specifically to protect and expand domestic production of the silicon carbide (SiC) and gallium nitride (GaN) semiconductors that power radar systems already aboard F-35 fighters, US Navy Aegis destroyers, and ballistic missile defense batteries, as detailed in Wolfspeed’s SEC Form 8-K filing. What makes the loan remarkable is not its size but its timing: Wolfspeed only emerged from Chapter 11 bankruptcy on September 29, 2025, fourteen months before the Pentagon agreed to be its primary long-term creditor.
This is not industrial policy for a future capability. It is retroactive insurance for infrastructure the US military is already depending on, right now, with no alternative domestic supplier capable of replacing it.
Wide Bandgap Semiconductors: Why Silicon Cannot Do What SiC and GaN Do
Silicon has dominated semiconductor manufacturing since the 1960s — and for good reason. It is cheap, abundant, and its manufacturing processes are extraordinarily mature. But silicon has a physical ceiling that determines where it stops being useful. Its bandgap, the energy gap between its valence and conduction bands, is approximately 1.12 electron volts (eV). That ceiling limits how much voltage silicon devices can handle before breaking down, how hot they can operate before performance degrades, and how efficiently they can switch at high power levels, as IEEE’s silicon carbide technology overview documents in detail.
Silicon carbide has a bandgap of approximately 3.26 eV — nearly three times wider. The difference in physical behavior is dramatic. SiC can sustain electric fields of roughly 2.2 megavolts per centimeter (MV/cm) before breakdown, approximately ten times what silicon can withstand. Its thermal conductivity of 3.7 watts per centimeter-kelvin (W/cm·K) exceeds that of copper, allowing heat to move away from active devices fast enough to sustain high-power continuous operation. Silicon devices begin to degrade at junction temperatures above roughly 150–175°C (302–347°F); SiC devices can operate at temperatures approaching 600°C (1,112°F), according to IEEE’s technical characterization of silicon carbide.
Gallium nitride built on a SiC substrate — GaN-on-SiC — combines the two materials’ strengths. GaN’s high electron mobility and saturation velocity enable microwave-frequency power amplification orders of magnitude more efficient than silicon can achieve. The SiC substrate removes the resulting heat fast enough to sustain continuous operation at the output powers that modern radar and electronic warfare systems require. The result is the transmit/receive module at the heart of every active electronically scanned array (AESA) radar in the US military arsenal, as PolicyRisk.com’s defense supply chain analysis confirms.
What Happens Inside a Weapons System When You Say “Semiconductor”
AESA radar — the technology that replaced mechanically rotating dish antennas on fifth-generation fighters and modern surface combatants — works by electronically steering a beam across thousands of individually controlled transmit/receive (T/R) modules. Each module contains a GaN-on-SiC amplifier that generates and receives a microwave pulse. The beam steers by controlling the phase of each module’s output — no moving parts, near-instantaneous direction changes, simultaneous tracking of multiple targets.
Defense industry analysts confirm that Wolfspeed’s GaN-on-SiC substrate powers the F-35’s APG-81 fire-control radar, the Raytheon AN/TPY-2 ballistic missile defense radar used in THAAD batteries, and the US Navy SPY-6 Aegis radar installed on Arleigh Burke-class destroyers. Re-qualifying those weapons systems to use a different semiconductor substrate would require years of testing, re-engineering, and regulatory approval — during which time production of those systems would be disrupted.
The Department of War’s 30-year loan, if finalized, would fund three specific expansions of Wolfspeed’s defense-relevant capabilities beyond its existing SiC materials and power device business: upgrading its GaN epitaxy lines for next-generation electronic warfare systems, advancing GaN-on-SiC radio-frequency epitaxial wafer technology, and developing domestic radiation-hardening capabilities for both current SiC and future GaN products, per the official OSC commitment letter.
Radiation hardening is the engineering process of making electronic components resistant to damage from high-energy ionizing radiation — the Van Allen belts, solar particle events, galactic cosmic rays, and the electromagnetic pulse (EMP) from nuclear detonations, as documented by the IEEE Technology Navigator’s radiation-hardening reference. Every military satellite, missile guidance system, and nuclear-survivable command-and-control platform requires rad-hard electronics. Wolfspeed currently has no domestic competitor for wide bandgap radiation-hardening specifically, making this element of the loan particularly significant for the space and strategic nuclear missions.
Why Silicon Carbide Is So Hard to Make
Understanding why Wolfspeed’s market position is difficult to replicate requires understanding the physics of SiC crystal growth. Silicon is grown by the Czochralski method: a seed crystal is dipped into molten silicon at about 1,415°C (2,579°F) and slowly pulled upward as the silicon solidifies into a cylindrical ingot. The process is well understood, fast, and scalable. A silicon ingot more than one meter (3.3 feet) long can be produced in roughly 48 hours.
Silicon carbide is fundamentally different. SiC cannot be melted and grown from a melt at practical pressures — its melting point exceeds 2,700°C (4,892°F) at 1 atmosphere, and at normal conditions SiC decomposes before it melts. Instead, SiC single-crystal boules are grown by sublimation: SiC powder is heated to approximately 2,300°C (4,172°F) in a sealed graphite crucible under low pressure of about 10–20 Torr, sublimating into vapor that recrystallizes on a cooler SiC seed crystal at roughly 2,200°C (3,992°F), as documented in Rigaku’s SiC wafer defect study.
Growth rates are extremely slow compared to silicon, and the resulting boule — typically only about 10 centimeters (3.9 inches) long — must be sliced into individual wafers. The process is susceptible to a class of defects called micropipes: channel-like voids running through the crystal that render devices fabricated above them inoperable. Controlling polytype — SiC occurs in more than 200 crystallographic forms, of which the electronics-relevant 4H variety requires precise temperature gradients to maintain — is an ongoing manufacturing challenge. Each step requires precision equipment capable of sustained operation at temperatures that would destroy conventional furnace components, as described in IEEE’s silicon carbide device overview.
The transition from 150mm (5.9-inch) to 200mm (7.9-inch) wafers that Wolfspeed pioneered at its Mohawk Valley Fab in Marcy, New York, matters because larger wafers produce substantially more semiconductor devices per growth run, reducing cost per device. Wolfspeed opened Mohawk Valley in April 2022 as the world’s first purpose-built, fully automated 200mm SiC fab — a facility designed to produce SiC power devices on wafers that no other manufacturer was yet making in volume. Ramping it has been slow and difficult, with persistent yield challenges and under-utilization costs that contributed to the company’s financial distress.
This is precisely why Wolfspeed’s market position is difficult for Chinese competitors to replicate quickly, despite their aggressive investment and pricing. TanKeBlue and SICC — the two Chinese producers who together captured approximately 34.4% of the global SiC substrate market in 2024, compared to Wolfspeed’s 33.7% — are progressing on standard-grade SiC materials, but Wolfspeed’s advantage in defense-grade quality, GaN-on-SiC RF epitaxy, and now radiation-hardening represents a separate and harder-to-replicate technology tier, according to TrendForce’s SiC substrate market report.
How the Loan Is Structured — and What Could Still Sink It
The commitment announced October 7 is not a check. It is a conditional letter from the Office of Strategic Capital, a DoD office designed to function as a development finance institution — providing patient, long-dated capital to strategically critical industrial companies in a way that commercial lenders cannot or will not match. The term of 30 years is itself a statement: the government is willing to hold this debt through multiple political cycles and market downturns, signaling that SiC/GaN supply chain security is a decades-long obligation, not a quarterly policy preference, per the OSC conditional commitment letter.
The loan would be structured as a senior secured delayed-draw term loan facility of up to $1.5 billion, with the first tranche of $600 million expected to refinance Wolfspeed’s secured notes maturing in 2030 — immediately removing the company’s most pressing debt maturity risk. Subsequent tranches are contingent on project milestones. Wolfspeed would be required to issue the DoW warrants to purchase up to 7.5% of its fully diluted equity, priced at volume-weighted average price and disbursed in proportion to funded tranches, giving the federal government a meaningful ownership stake as a condition of each funding round, as specified in Wolfspeed’s SEC Form 8-K filing.
Wolfspeed’s shares surged approximately 27% in extended trading on October 7 following the announcement. At the time, the company’s entire market capitalization was approximately $1.66 billion — meaning the proposed loan nearly matched the value of its publicly traded equity. However, the commitment remains conditional on the completion of due diligence, the negotiation and execution of definitive agreements, government appropriations, and the consent of Wolfspeed’s existing lenders. The company stated explicitly in its 8-K that there is no assurance any financing will ultimately be provided.
CFO Gregor van Issum called the conditional commitment “another significant milestone in our ongoing efforts to optimize Wolfspeed’s capital structure and improve our financial foundation,” noting the long-dated capital would support the company’s strategic priorities and improve financial flexibility, according to Wolfspeed’s official SEC press release.
What Bankruptcy Revealed: A Strategic Asset That Couldn’t Pay Its Bills
Wolfspeed’s bankruptcy was one of the more jarring industrial failures in recent semiconductor history, not because of fraud or mismanagement in any traditional sense, but because the company built the right technology for the future while the markets it was counting on materialized more slowly than expected.
The company — originally founded in 1987 as Cree Inc. and renamed Wolfspeed in October 2021 after divesting its LED and lighting businesses — placed an enormous capital expansion bet in 2021 and 2022, building the Mohawk Valley Fab and designing the John Palmour Manufacturing Center in Siler City, North Carolina as the world’s largest SiC materials factory, designed to increase production capacity by more than tenfold from prior output. The capital investment totaled billions of dollars financed with debt, based on projections of electric vehicle adoption and industrial power demand that failed to materialize on schedule.
Then Chinese SiC producers TanKeBlue and SICC aggressively expanded capacity and cut prices, driving down market revenues. Global N-type SiC substrate revenue fell 9% year-over-year to $1.04 billion in 2024 as competition intensified and demand softened in automotive and industrial markets, per TrendForce’s May 2025 market analysis. Wolfspeed’s debt load of approximately $6.5 billion became unsustainable. The company cut approximately 20% of its workforce in November 2024, then filed for Chapter 11 in the Southern District of Texas on June 30, 2025.
The restructuring was pre-packaged and efficient. More than 97% of senior secured noteholders and approximately 67% of convertible noteholders supported the plan, with Renesas Electronics providing 100% consent as part of a negotiated agreement that gave Renesas equity in the reorganized company. The court confirmed the reorganization plan on September 8, 2025, and Wolfspeed exited Chapter 11 bankruptcy protection on September 29, 2025, having eliminated approximately $4.6 billion — roughly 70% — of its total debt and reduced annual cash interest payments by approximately 60%. Under new CEO Robert Feurle and new CFO Gregor van Issum, the company reset its strategy around its highest-value markets: defense, AI data centers, and next-generation industrial power.
One early indicator that the reset was working: AI data center revenue more than doubled year over year in fiscal 2026, as the transition to 800-volt power architectures inside hyperscale data centers increased demand for SiC power devices capable of higher voltage and greater efficiency than silicon allows.
Where the Pentagon’s Money Fits in the Broader SiC Race
The DoW loan does not exist in isolation. It is part of a broader federal effort to treat wide bandgap semiconductors as strategic national infrastructure. The 2022 CHIPS and Science Act directed $39 billion toward domestic chip manufacturing incentives through the Department of Commerce, with an additional $2 billion specifically for the Department of Defense and DARPA through the Microelectronics Commons program for defense-unique semiconductor applications, as the National Academies’ semiconductor policy review documents.
The CHIPS Act funding stream and the OSC loan stream represent two different government instruments targeting the same strategic problem. CHIPS Act grants are civilian commerce tools — they come from Commerce, are designed to encourage commercial semiconductor production, and come with workforce, community benefit, and domestic content strings. The OSC loan is a defense finance instrument, functioning more like the Export-Import Bank or the Development Finance Corporation but aimed inward at domestic industrial capacity that the defense mission requires. The terms — 30-year tenor, equity warrants, conditionality tied to defense milestones — are the tools of a patient strategic investor, not a commercial lender, per the official DoW commitment letter.
For Wolfspeed, the DoW loan, if finalized, would layer a new source of long-dated capital on top of the restructured balance sheet and serve as the primary mechanism for funding the GaN and radiation-hardening investments the company’s defense business requires. Whether it materializes depends on a negotiation process — definitive agreements, due diligence, appropriations — that could still fail or produce substantially different terms than the commitment letter describes.
For now, the announcement signals something more durable than a transaction: the United States government has classified wide bandgap semiconductor manufacturing as an element of national defense infrastructure it is not willing to lose — and has decided that Wolfspeed, however troubled its recent history, is the best available bet for keeping that infrastructure domestic.
Frequently Asked Questions
What is GaN-on-SiC, and why does the US military need it?
Gallium nitride (GaN) deposited on a silicon carbide (SiC) substrate is the foundational material for the transmit/receive modules that power active electronically scanned array (AESA) radar. These modules require semiconductor devices that can amplify microwave-frequency signals at high power levels continuously without overheating. Silicon cannot meet those specifications — it lacks the breakdown voltage and thermal conductivity that defense radar systems demand. GaN provides the microwave performance; the SiC substrate removes the heat fast enough to sustain it. Defense industry analysts have confirmed that the F-35 APG-81 fire-control radar, the Raytheon AN/TPY-2 ballistic missile defense radar, and the US Navy SPY-6 Aegis radar all use GaN-on-SiC transmit/receive modules. There is currently no qualified domestic alternative supplier of these materials at the required quality and scale.
Why did Wolfspeed — the dominant US SiC manufacturer — go bankrupt?
Wolfspeed bet billions of dollars of borrowed capital on two assumptions that both proved premature: that electric vehicle adoption would accelerate on schedule, creating high demand for SiC power devices in EV traction inverters, and that industrial power markets would absorb its expanded production quickly. Both markets disappointed. Simultaneously, Chinese producers TanKeBlue and SICC dramatically expanded SiC wafer capacity and cut prices aggressively, compressing margins across the industry and driving global SiC substrate revenue down 9% in 2024 to $1.04 billion, according to TrendForce. With approximately $6.5 billion in total debt accumulated during its capital expansion program, Wolfspeed ran out of road and filed for Chapter 11 in June 2025. It emerged in September 2025 having shed roughly $4.6 billion of that debt — about 70% — in a prepackaged restructuring supported by most of its major creditors.
What does “conditional commitment letter” mean — is this loan actually happening?
Not necessarily, yet. A conditional commitment letter is a formal expression of intent from the DoW’s Office of Strategic Capital, not a completed loan agreement. Before any money moves, the parties must negotiate and execute definitive loan documents, Wolfspeed must satisfy financial and operational conditions (including a co-investment requirement), the government must secure the relevant appropriations, and Wolfspeed’s existing lenders must consent to the new senior secured debt. Wolfspeed’s own Form 8-K states explicitly that “there can be no assurance that definitive agreements will be executed or that any financing will be provided.” The commitment letter is a meaningful signal of government intent — and it sent Wolfspeed’s stock up approximately 27% in after-hours trading — but it is not a guarantee.
What is radiation hardening, and why does the Pentagon want Wolfspeed to develop it for SiC and GaN chips?
Radiation hardening is the engineering practice of making electronic components resistant to damage from ionizing radiation — high-energy particles and gamma rays that can corrupt stored data, cause transistors to latch up, or degrade device performance over time. Satellites in the Van Allen radiation belts, missiles crossing high-altitude nuclear environments, and command systems designed to survive nuclear detonations all require rad-hard electronics. Silicon carbide’s wider bandgap provides some inherent radiation tolerance advantages over conventional silicon, but commercial SiC chips are not automatically rad-hard. Full qualification requires specialized design rules, testing to military standards, and documentation — a process Wolfspeed has not yet systematically completed for its SiC and GaN product lines. The DoW loan specifically funds that development, which would create a domestic source of radiation-hardened wide bandgap semiconductors that currently does not exist at commercial scale in the United States.