HomeAuto EU Picks Belgian Startup Over Airbus to Build Its Sovereign Satellite Constellation
EU Picks Belgian Startup Over Airbus to Build Its Sovereign Satellite Constellation
September 17, 2026:
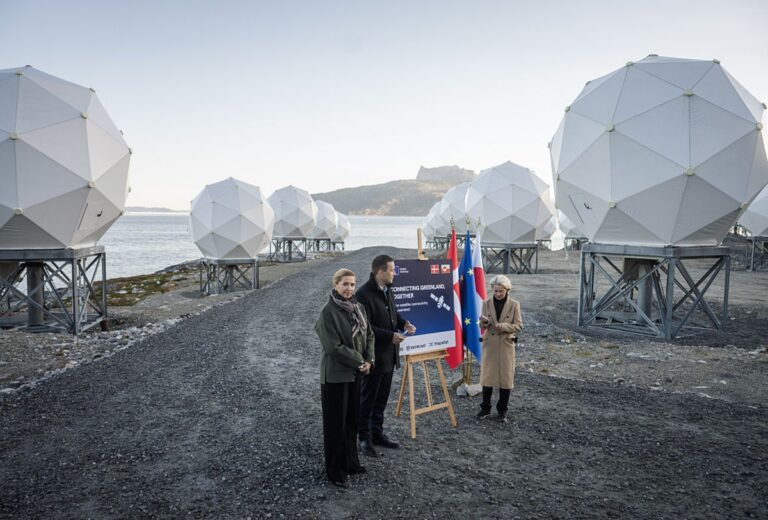
Mads Claus Rasmussen/Ritzau Scanpix / AFP via Getty Images
Europe’s only operating low Earth orbit broadband network will grow to approximately 1,300 active satellites by 2030 before its customers are handed over to the European Union’s forthcoming IRIS2 constellation — and the company that will build most of that IRIS2 infrastructure is not Airbus. Eutelsat CEO Jean-François Fallacher detailed the constellation roadmap at World Space Business Week in Paris on September 15.
Speaking at World Space Business Week in Paris on September 15, Eutelsat Group CEO Jean-François Fallacher laid out the most detailed public account yet of how the company plans to keep its OneWeb constellation commercially viable through the decade, while Aerospacelab — a Belgian startup incorporated in 2018 — prepares to build 264 of the 330 planned low Earth orbit (LEO) satellites for IRIS2, a contract worth €2.4 billion (approximately $2.8 billion) that most industry observers expected would go to Airbus.
For a US reader, this is the story of whether Europe can mount a credible alternative to SpaceX’s Starlink before Starlink locks in the global enterprise and government satellite broadband market for a generation — and whether the industrial structure Europe is betting on to deliver that alternative is built to last.
OneWeb’s Aging Fleet and the Case for Replenishment
OneWeb operates 654 first-generation satellites in twelve orbital planes at roughly 1,200 kilometers (746 miles) altitude — about 600 of those for active coverage and the rest for redundancy. The constellation was completed in early 2023 and received a top-up batch of 20 satellites in October 2024, but the fundamental challenge for Eutelsat is that LEO satellites are not permanent infrastructure — orbital drag, radiation exposure, and battery degradation give each unit a designed operational life of roughly five to seven years. The oldest OneWeb satellites launched in 2019 and 2020 are already approaching or past that threshold.
This is not an optional upgrade. Without a replenishment program, Eutelsat’s global coverage would degrade through the late 2020s at precisely the moment the IRIS2 program is expected to reach initial operational capability. The company’s solution is a sequential procurement strategy that keeps the replacement pipeline full while avoiding the capital risk of designing a fully proprietary second-generation architecture from scratch.
The program consists of three tranches, all contracted with Airbus Defence and Space and all manufactured at Airbus’s facility in Toulouse, France — a shift from the original Florida joint-venture production line. A first contract signed in December 2024 covered 100 satellites for service continuity. A second contract announced in January 2026 added 340 more LEO satellites. The third authorization, announced September 10, brings in 229 additional spacecraft, which Eutelsat designates as Gen 1.5, bringing the total Airbus order book to 669 vehicles. The estimated investment for the latest tranche alone is approximately €1 billion (about $1.16 billion), backed by a €975 million Bpifrance export credit facility guaranteed by the French state.
First deliveries from the 440-satellite tranche are expected by the end of calendar 2026, with Ariane 64 launches booked for 2027 and 2028 to sustain the replenishment cadence.
What Digital Channelizers Actually Do — and Why It Changes the Architecture
The Gen 1.5 satellites are not simple like-for-like replacements of their predecessors. Their key architectural difference is the shift from analog to digital onboard signal processing — and understanding why this matters explains how Eutelsat’s replenishment plan becomes a genuine technology upgrade rather than a maintenance program.
In a conventional analog satellite, incoming radio signals from ground terminals are filtered, amplified, and routed to output beams using fixed hardware — essentially hardwired frequency plans baked into the satellite before launch. If market demand shifts, if a customer needs different bandwidth allocations, or if interference from a competing signal requires the satellite to change its frequency plan, there is essentially nothing the operator can do without physically replacing hardware.
Digital channelizers change this. Eutelsat has contracted Ramon.Space to supply onboard digital communication channelizer systems — specifically its NuComm product line — for the OneWeb replacement satellites, with NuComm flight sets launching late 2026. The NuComm system uses digital signal processing to convert incoming wideband signals into discrete frequency sub-bands in software, enabling three capabilities that analog hardware cannot provide: any-to-any beam switching (any input from any ground terminal can be routed to any output beam dynamically); in-orbit reprogramming (frequency plans, power allocations, and routing tables can be updated by ground command after launch); and hosted payload partitioning (logical frequency segments can be allocated to third-party operators — including government agencies — without any physical hardware separation).
That last capability is not incidental. One of the hosted payloads already contracted for the Gen 1.5 satellites is a dedicated defense package procured by the French Ministry of Armed Forces under the NEXUS program, discussed further below.
The reason this matters architecturally is that digital channelization is also the baseline assumption for IRIS2. By building the OneWeb replenishment satellites with software-defined radio interfaces and in-orbit programmability, Eutelsat ensures that customers who adopt OneWeb capacity during the bridge period will be using terminal equipment and service architectures that are forward-compatible with IRIS2’s approach — reducing migration friction when the handover begins in the early 2030s.
What the Aerospacelab Win Over Airbus Signals
The most significant industrial fact in this story is not the Eutelsat roadmap — it is who is building most of IRIS2’s LEO layer, and why Airbus did not get that contract.
Belgium’s Aerospacelab, founded in 2018 by CEO Benoît Deper, has been selected as the prime contractor for 264 of the 330 planned LEO satellites in the IRIS2 constellation, under a contract worth €2.4 billion (approximately $2.8 billion). That represents approximately 76% of the LEO layer, and it went to a company that had fewer than eight years of operating history at the time of selection. Airbus — which has manufactured all of the existing OneWeb first-generation satellites and is currently building the 669-satellite replenishment program — received only a smaller contract for 66 military Ka-band LEO satellites for IRIS2, to be delivered in 2029.
“The selection of Aerospacelab for IRIS2 reflects a deliberate industrial choice, a defining moment for Europe as a whole,” Deper said in a statement issued September 10. “Institutions are now also placing their trust in a new generation of space manufacturers: companies like Aerospacelab, built from the ground up to deliver satellite infrastructure at scale and speed.”
The industrial logic behind that choice mirrors what SpaceX established with Starlink: a purpose-built production facility — Aerospacelab’s Megafactory in Mont-Saint-Guibert, Belgium — designed for serial, standardized satellite manufacturing rather than bespoke per-program engineering. At €2.4 billion for 264 satellites, the implied average unit value is roughly €9.1 million (approximately $10.6 million) per satellite, a fraction of what traditional large-platform satellite manufacture costs. The Megafactory is specifically designed to produce satellites at the cadence and cost profile this contract demands.
Industry observers had widely expected Airbus to absorb the IRIS2 LEO work as a natural extension of its existing OneWeb production run in Toulouse — a seamless continuation that would have leveraged established tooling, supply chains, and workforce. That the European Commission and Eutelsat instead chose a startup signals a deliberate bet on the serial-production model over the incumbent. Advanced Television noted at the time that industry consensus had favored Airbus for the IRIS2 award. Whether Aerospacelab can deliver 264 fully integrated satellites on schedule will be the defining industrial test of this decade for European smallsat manufacturing.
The IRIS2 Industrial Stack: Who Is Building Europe’s Sovereign Constellation
IRIS2 — Infrastructure for Resilience, Interconnectivity and Security by Satellite — is the EU’s flagship sovereign broadband program, managed through a public-private partnership concession signed in December 2024 by the SpaceRISE consortium, which comprises Eutelsat, SES, and Hispasat. The program is planned as Europe’s third flagship space initiative after Galileo (navigation) and Copernicus (Earth observation).
The full constellation will consist of 348 satellites: 330 in LEO and 18 in medium Earth orbit (MEO). Breaking down the industrial assignments:
Aerospacelab (Belgium): 264 dual Ku/Ka-band LEO platforms — the commercial layer of the constellation. Thales Alenia Space (France/Italy) will build the payloads for all 330 LEO satellites, under a contract worth approximately €500 million (about $580 million). Airbus Defence and Space: 66 Ka-band military LEO satellites — the government/defense layer. SES has contracted OHB SE (Germany) for the 18 MEO spacecraft in a deal worth approximately €1 billion (about $1.16 billion).
The European Commission confirmed all IRIS2 satellite orders on September 13, 2026. The total IRIS2 program budget has grown substantially since the program’s initial scoping — current estimates stand at €15.6 billion (approximately $18.1 billion), reflecting both scope expansion and the complexity of building a multi-orbit system with military-grade security requirements and sovereign resilience obligations. Commercial Ku-band service from the LEO layer is targeted for mid-2032.
Does the Military Already Depend on OneWeb?
One of the understated facts in this story is that OneWeb is not just a commercial broadband network waiting for its successor to be built. It is already operational military infrastructure.
The NEXUS program — short for Neo-Espace pour de multiples Usages Sécurisés (New Space for Multiple Secure Uses) — is a French Ministry of Armed Forces initiative to combine France’s sovereign geostationary satellite system (Syracuse) with commercial LEO capacity from OneWeb while IRIS2 is still being deployed. In June 2025, the French Directorate General of Armaments (DGA) signed a ten-year NEXUS framework agreement with Eutelsat valued at up to €1 billion (approximately $1.16 billion), covering priority-access OneWeb capacity, hosted defense payloads on upcoming satellites, and operational security enhancements for military-grade use.
The first call-off contract under that framework — designated CENTAURE — was signed in June 2026, with a ceiling of approximately €350 million (about $406 million) over eight years and a firm initial commitment of €138 million (approximately $160 million) for the first four years. The contract explicitly positions itself as an immediately operational military satellite solution ahead of IRIS2.
General Jérôme Bellanger of the French armed forces has said he hoped IRIS2 delays would not extend to 2035 — an acknowledgment that the French military is actively planning for a potential IRIS2 slip beyond its 2030-2032 window. For American readers evaluating how dependent European military communications have become on non-US commercial infrastructure, the CENTAURE contract is the clearest data point available.
Can Aerospacelab Actually Deliver at This Scale?
The honest answer is that no one knows yet — because delivering 264 satellites at serial-production scale within a four-year window is something no European manufacturer has done. SpaceX built the production capability for Starlink satellites over multiple years, with significant early failures and ramp-up friction. Aerospacelab’s Megafactory in Mont-Saint-Guibert is currently being completed; the company raised $110 million Series B in 2025 to fund the buildout.
European telecoms operators Orange and Deutsche Telekom have already signaled that their adoption of IRIS2 capacity will depend on whether the constellation can compete commercially with Starlink on cost and performance — not just provide European sovereignty as a selling point. If Aerospacelab’s production ramp encounters the delays that typically accompany first-time large-scale satellite manufacturing, the IRIS2 schedule pressure will compound rapidly.
Meanwhile, Starlink continues to grow. As of August 2026, SpaceX’s constellation stands at approximately 10,900 Starlink satellites — a fleet more than sixteen times the size of OneWeb’s current coverage layer. Amazon’s Project Kuiper is also launching. Eutelsat’s competitive positioning relies on being the enterprise and government alternative that offers managed service levels, security assurances, and European sovereignty guarantees — not consumer broadband volume. For that narrower market, the 1,300-satellite OneWeb fleet may be sufficient.
What Fallacher’s September 15 keynote made explicit for the first time is that Eutelsat has no intention of building a proprietary Gen 2 architecture to compete with Starlink at scale. The 1,300-satellite OneWeb peak is the ceiling, not the floor. IRIS2 — with a capacity Eutelsat describes as more than twice OneWeb’s current throughput — is the destination.
For its most recent fiscal year ended June 2026, Eutelsat’s LEO revenue reached €297 million (approximately $344 million), up 69.5 percent year-on-year, and now represents 25 percent of total group revenue. The legacy geostationary business continues to decline. The company has completed a comprehensive ~€5 billion (approximately $5.8 billion) financial restructuring that stabilized its balance sheet, with the French government holding 29.65 percent of shares as the largest single shareholder.
The path from where OneWeb is today — 600 satellites providing coverage, generating a quarter of Eutelsat’s revenue, and serving the French military as a bridge to something bigger — to a 1,300-satellite peak and then a handover to a 330-satellite LEO layer built by a Belgian startup is either the most credible European answer to Starlink yet assembled, or a €15.6 billion (~$18.1 billion) bet on a manufacturing model and an industrial newcomer that has never been tested at this scale. The Megafactory answer comes in 2030.
Frequently Asked Questions
What is IRIS2 and how is it different from OneWeb?
IRIS2 (Infrastructure for Resilience, Interconnectivity and Security by Satellite) is the European Union’s planned sovereign multi-orbit broadband constellation, managed through a public-private partnership called SpaceRISE, with Eutelsat, SES, and Hispasat as the consortium operators. Unlike OneWeb — a commercial constellation focused on enterprise, government, and mobility customers — IRIS2 will have explicit EU sovereignty requirements, military-grade security, and government-reserved capacity for EU member states. It will consist of 330 LEO satellites and 18 MEO satellites, with commercial Ku-band service targeted for mid-2032. OneWeb is the bridge: Eutelsat plans to sustain OneWeb at approximately 1,300 active satellites through 2030 before migrating customers to IRIS2 infrastructure.
What does a digital channelizer on a satellite actually do, and why does it matter for enterprise customers?
A digital channelizer replaces the fixed analog frequency-routing hardware in a conventional satellite with software-configurable signal processing. Where an analog satellite’s frequency plans are set at manufacturing and cannot be changed after launch, a digital channelizer allows the satellite operator to update bandwidth allocations, beam routing, and power distributions by ground command — in orbit, with no physical access required. For enterprise customers, this means the satellite can adapt to changing demand patterns, respond to interference, and support isolated logical channels for different customers (including government agencies) without hardware swaps. The Gen 1.5 OneWeb satellites will use Ramon.Space’s NuComm digital channelizer system, with first launches expected before the end of calendar 2026.
Why did Aerospacelab beat Airbus for the IRIS2 LEO contract, and what does that mean for European space manufacturing?
Aerospacelab’s Megafactory model — purpose-built serial production of standardized satellite platforms at high volume — offered a unit cost and delivery schedule that Airbus’s more traditional large-program manufacturing approach could not match. The EC and Eutelsat made a deliberate choice to bet on the SpaceX-style serial production model as implemented by a European newcomer, rather than continuing to assign major constellation work to the incumbent prime contractor. Whether Aerospacelab can deliver 264 fully integrated LEO satellites on schedule by 2030 will determine whether this industrial policy bet pays off — and potentially reshape how all future EU constellation contracts are awarded.
How much of OneWeb’s capacity does the French military already use, and what happens to that if IRIS2 slips?
France’s DGA signed a ten-year framework agreement (NEXUS) with Eutelsat in June 2025, valued at up to €1 billion (approximately $1.16 billion), covering priority military access to OneWeb LEO capacity, hosted defense payloads on the Gen 1.5 satellites, and security enhancements for military-grade use. The first call-off contract under that framework (CENTAURE, signed June 2026) commits approximately €138 million (about $160 million) over four years. The French military has explicitly described the arrangement as a bridge until IRIS2 is operational — but General Jérôme Bellanger has acknowledged concern that IRIS2 could slip as far as 2035. If that happens, the NEXUS framework is structured to extend military OneWeb access accordingly, which is one reason the 229-satellite Gen 1.5 order includes hosted payload capabilities from the outset.